 Μake us preferred on Google
Greece is now borrowing at a lower yield than France on 10-year government bonds, an unusual development that reflects changing investor assessments of the two countries’ fiscal outlooks and political risks amid renewed turbulence in European markets.
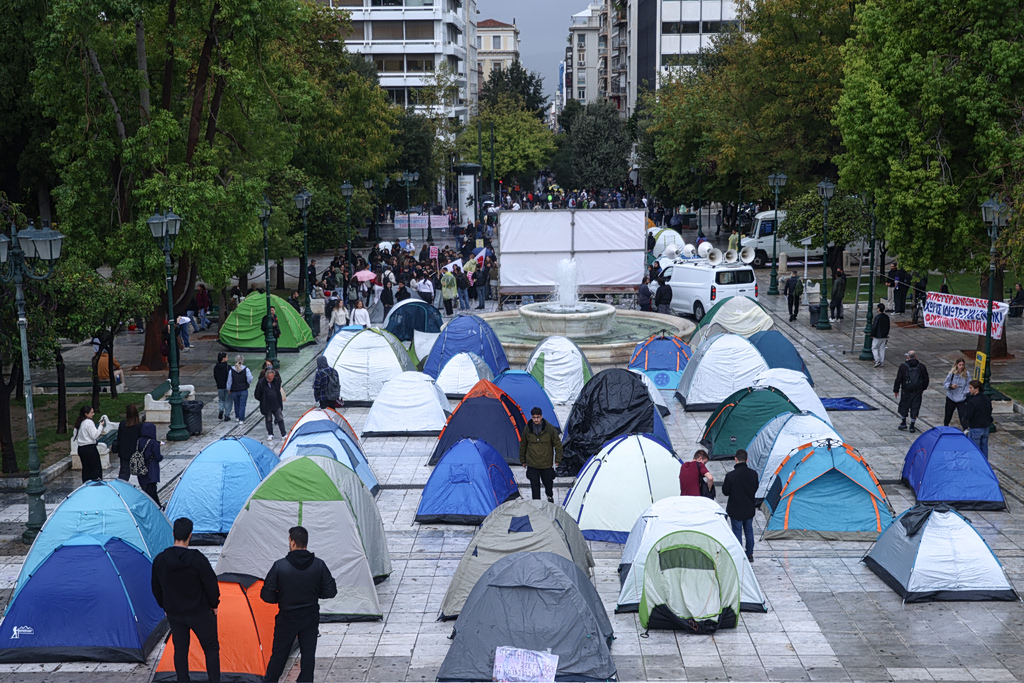
The shift comes as protests and political uncertainty in France push up borrowing costs for the eurozone’s second-largest economy. At the same time, an energy-price surge is fueling inflation concerns, while governments across Europe face growing refinancing needs and tighter financial conditions.
Although Greece has benefited from its lower relative borrowing costs, its own bond yields have risen significantly in recent weeks, highlighting how the market turmoil is affecting the wider eurozone.
French borrowing costs climb amid political uncertainty
France’s 10-year government bond yield returned to nearly 4.9% on Monday, rising by about 13 basis points following weekend unrest. Earlier in October, the yield had reached 4.99%, its highest level since 2002.
The spread between French and German 10-year bond yields widened to 146 basis points, indicating the additional return investors are demanding to hold French debt. Italian borrowing costs also increased, with the 10-year yield moving toward 4.58%.
France faces a difficult combination of public discontent, weak economic growth and limited political room to implement fiscal reforms. Rising living costs and pressure on household incomes have fueled protests, while the government needs to reduce its budget deficit without triggering further social opposition.
The resulting tension is increasingly reflected in bond markets. Measures to address protesters’ demands for stronger purchasing power and better public services could complicate efforts to rein in public spending. Conversely, stricter fiscal measures risk intensifying protests and political instability.
Investors’ concerns center not so much on France’s immediate ability to service its debt as on whether the country can stabilize its public finances.
France faces a difficult budget challenge
France’s proposed 2027 budget calls for 54 billion euros in fiscal adjustments, aiming to reduce the deficit from 5.4% of gross domestic product (GDP) in 2026 to 5% in 2027.
Achieving that goal will be difficult amid sluggish growth, a fragmented parliament and the approach of the 2027 presidential election.
France’s financing requirements are also increasing. The government plans to raise 340 billion euros through medium- and long-term bond issuance in 2027, net of buybacks, compared with an initial program of 310 billion euros for 2026. The planned amount would set a new record.
Debt-servicing costs are expected to rise from 79.2 billion euros this year to 91.2 billion euros in 2027, an increase of 12 billion euros in a single year. The additional burden could further restrict the government’s ability to fund social programs and development spending.
Investors are also watching Moody’s scheduled credit rating review on October 23. The possibility of another downgrade is adding to market caution. While a negative decision would not automatically trigger a fiscal crisis, it could increase pressure on French borrowing costs.
Energy crisis complicates the ECB’s response
The turmoil in France is unfolding as renewed energy-price pressures threaten to push inflation higher across Europe.
Natural gas prices have reached 87.20 euros per megawatt-hour, while European gas storage levels have fallen below 74%, raising concerns about another expensive winter.
Higher energy costs reduce households’ disposable income, increase production expenses and create pressure on governments to provide additional support. These demands come as financial markets expect governments to maintain fiscal discipline.
The European Central Bank (ECB) is also facing competing pressures. Renewed inflation has brought its deposit rate to 2.5%, limiting the scope for monetary easing. Meanwhile, the ECB is shrinking its bond holdings without reinvesting proceeds from maturing securities, leaving private investors to absorb a larger share of new government debt issuance.
As a result, governments must meet greater financing needs in a market that is less willing to lend at the borrowing costs seen in previous years. Long-term yields can tighten financial conditions even without another increase in benchmark interest rates.
ECB President Christine Lagarde has emphasized that addressing France’s fiscal problems is primarily the responsibility of the French government. The bank’s monetary policy tools do not guarantee that it will intervene to contain rising French yields regardless of the country’s fiscal decisions.
Why Greek bonds are outperforming French debt
Greece’s lower 10-year bond yield than France’s marks a notable shift in how investors assess the two countries. Although Greek public debt remains significantly higher as a share of GDP, the relative pricing reflects differences in their fiscal outlooks and perceived political risks.
However, Greece has not escaped the broader rise in European borrowing costs.
The yield on Greek 10-year government bonds stood at 4.217% on September 21. It climbed to 4.535% on Oct. 1 before moving to around 4.4% on Oct. 19. Although the yield has eased from its early-October peak, the cost of new borrowing remains elevated.
Greece may now be viewed as less risky than France for this particular bond maturity, but it is still paying more to borrow than it was a month earlier.
Greece’s debt structure offers some protection
The impact of higher yields on Greece’s government budget is moderated by the country’s cash reserves and the long maturity of its public debt.
According to the figures cited in the report, Greece’s debt has an average remaining maturity of 18.28 years and an average repricing period of 17.68 years. This structure limits how quickly changes in market yields translate into higher interest expenses.
The Public Debt Management Agency has estimated the average annual servicing cost of the existing debt portfolio at 1.94%.
That figure, however, reflects the cost of servicing outstanding debt, not the interest rate at which Greece can borrow today. New bond issues and refinancing gradually incorporate investors’ higher yield demands.
Higher borrowing costs weigh on businesses
The consequences extend beyond government financing. Greek businesses are facing more expensive energy, higher financing costs and increased working-capital needs.
As companies direct more borrowing toward covering day-to-day operating expenses, less funding may be available for productive investment, limiting opportunities for expansion and growth.
The developments in France underscore a wider challenge for European governments. They need additional resources to address the cost of living, finance investment and support households, but must secure that funding in an environment of more expensive borrowing and tighter fiscal constraints.