 Μake us preferred on Google
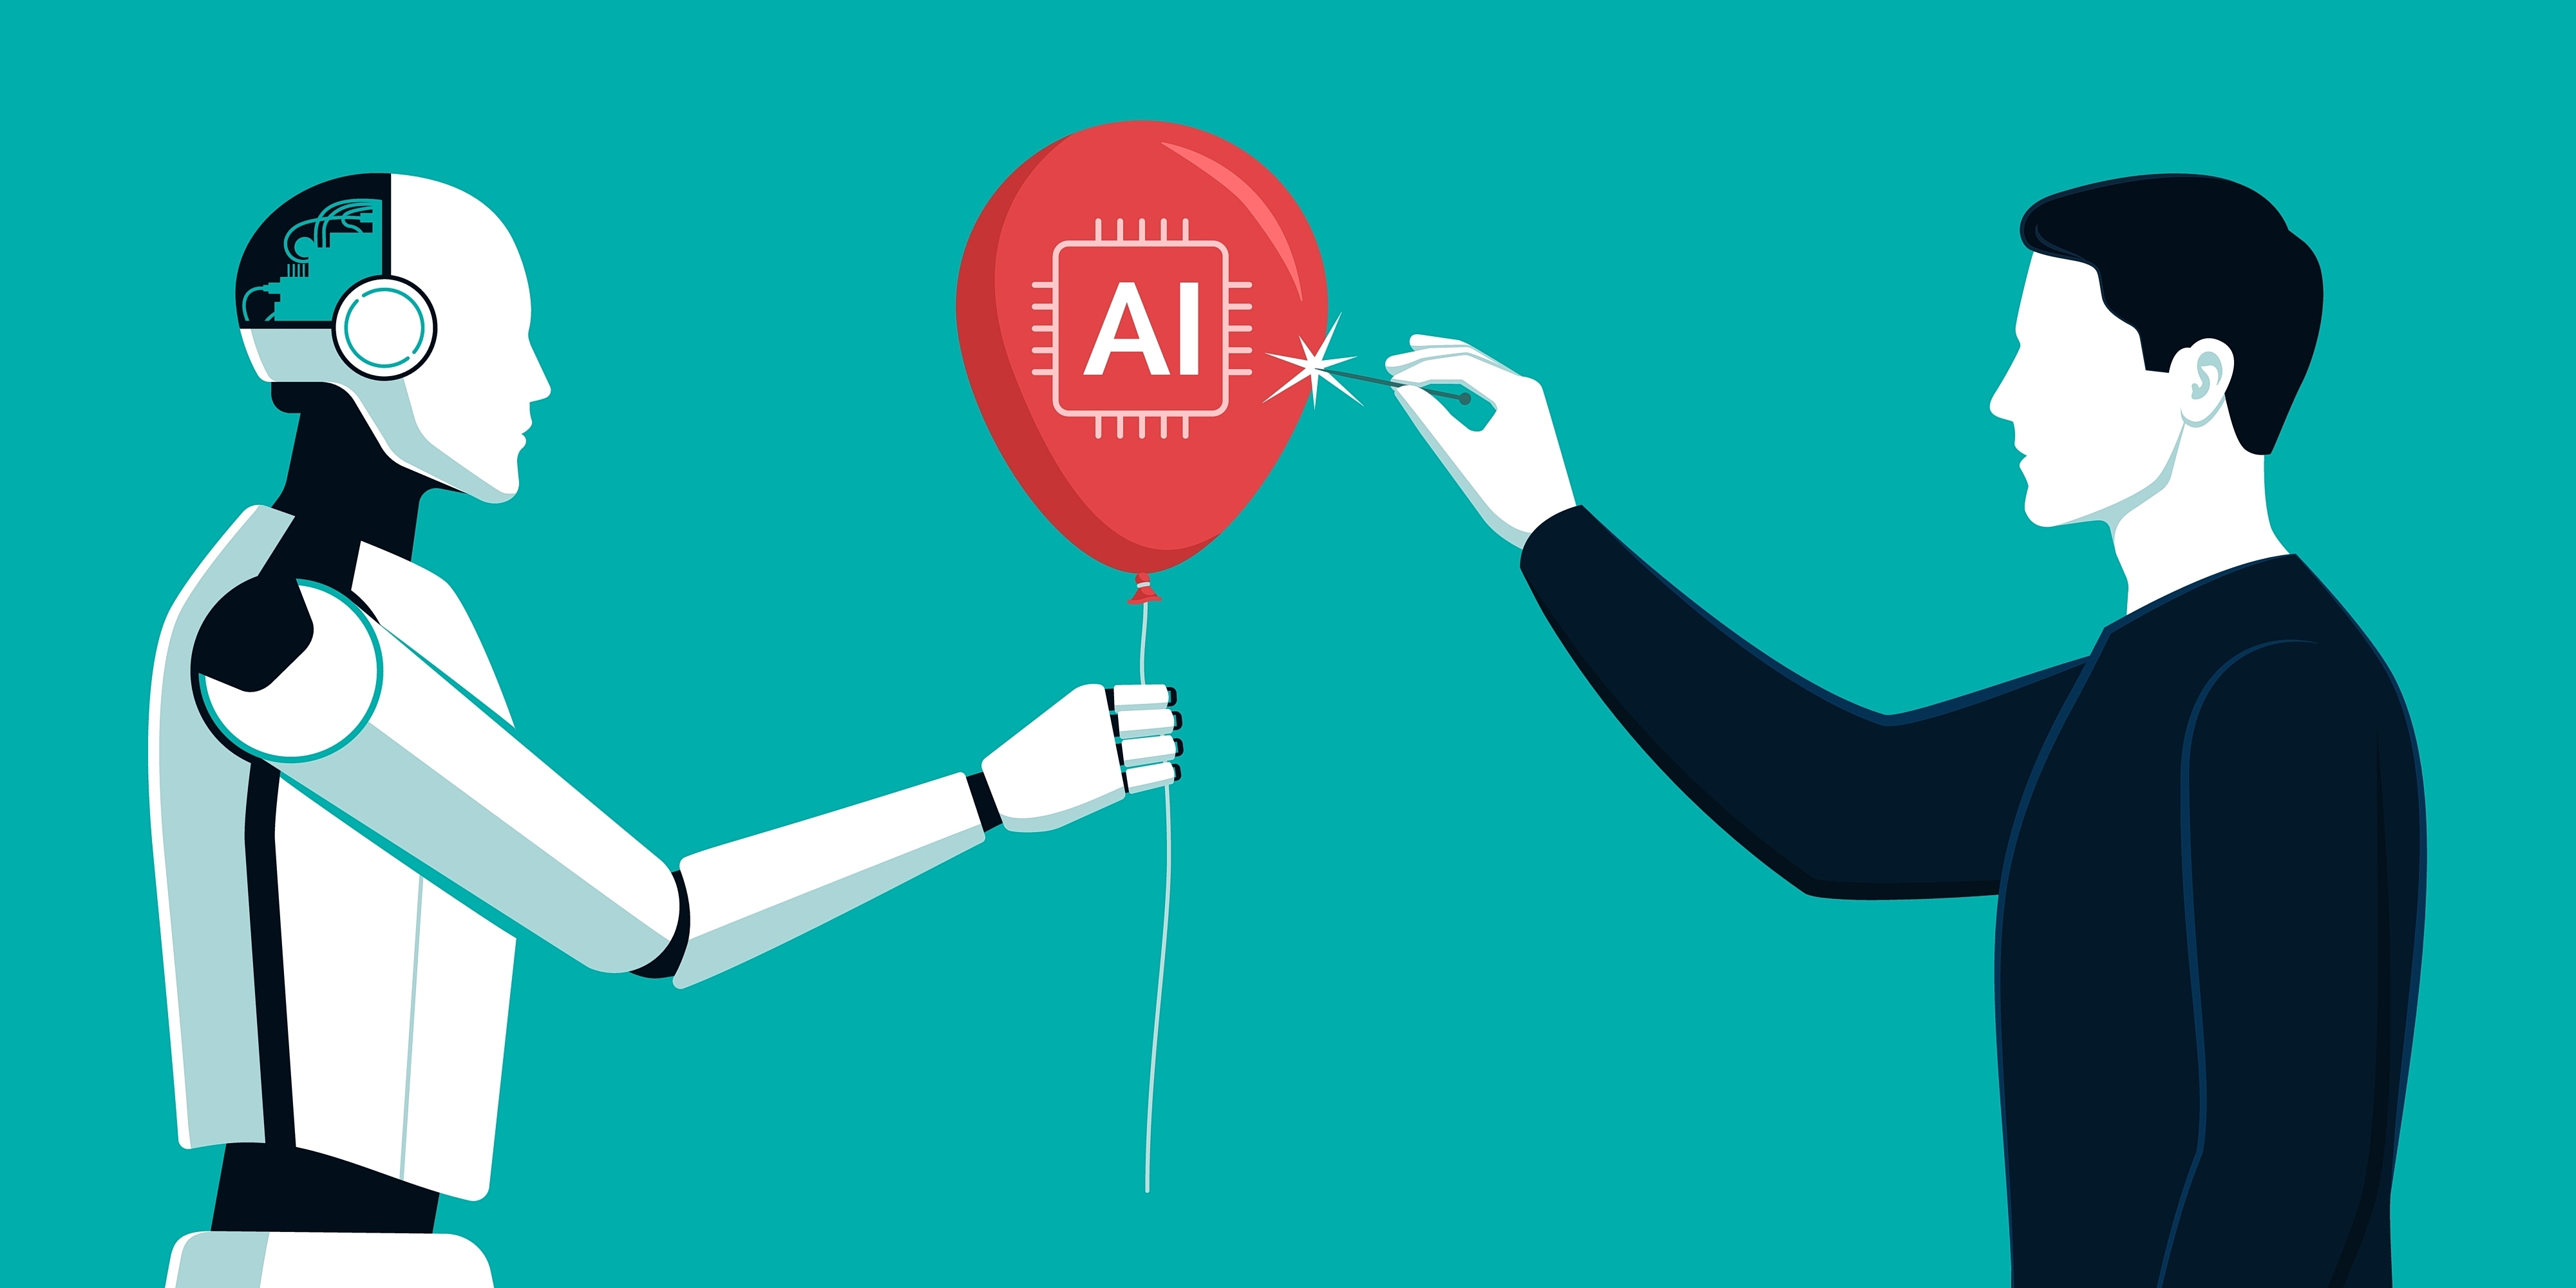
It is a truth universally acknowledged that new, transformative technologies rewrite the rules of finance. At least, that is what we are told in countless commentaries, social media posts and official submissions to regulators, prompted by the current investment boom in artificial intelligence (AI). That boom may well turn out to be a bubble.
Economic fundamentals cannot be ignored forever. For those too young to remember the collapse of internet (dot-com) companies in the early 2000s, a group that I suspect includes almost all of today’s AI industry leaders, the investment frenzy of the late 1990s offers important lessons.
We are seeing the same circular financing in the AI boom. Anthropic buys computing power, based on Nvidia microchips, from a company in which Nvidia is a major investor. Microsoft has invested more than $13 billion in OpenAI, while at the same time selling it cloud services through its Azure division. Is this a case of financial innovation? Or is it an unsustainable boom-and-bust mechanism?
At the macroeconomic level, the numbers speak for themselves. It is estimated that justifying the trillions of dollars being spent on AI infrastructure will require annual revenue of more than $2.5 trillion by 2030. These cash flows must come from customers paying to use AI services in order to increase their own revenue, which, broadly speaking, means cutting costs (mainly payroll) from their bottom line.
However, removing trillions of dollars from payroll spending in the West would cause social unrest. And given the current volume of private debt, a financial collapse would very likely follow. Alternatively, markets may conclude that AI companies cannot repay their debts, in which case the sequence of events would be reversed: a possibly unprecedented financial collapse, leading to social unrest.
I use the word “unprecedented” for two reasons. First, debt exposure today is significantly greater than in 2001, which makes the situation more similar to the period before the 2008 global financial crisis. Second, wealth today is far more concentrated in the technology, media and telecommunications sector.
If the financial sector decides to stop funding AI, will capital be freed up for investment in other areas, such as the productive economy or youth employment? Given that the United Kingdom is placing AI at the center of its ambitions ahead of its G20 presidency in 2027, its agenda must include safety, standards and planning for a possible crash.
Chi Onwurah is a Labour Party member of the U.K. Parliament and chair of the House of Commons Science, Innovation and Technology Committee.